

Intuit Credit Karma
by Credit Karma, LLC
4.7
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.7
- Price
- Free
- Download
- 50.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
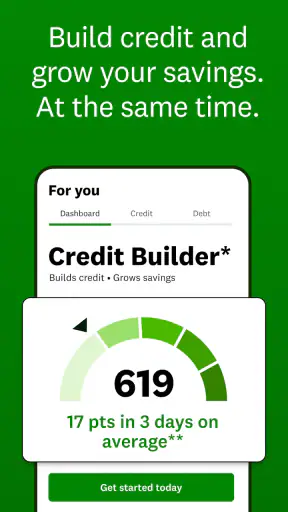
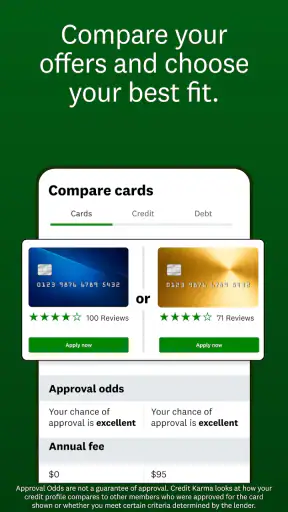
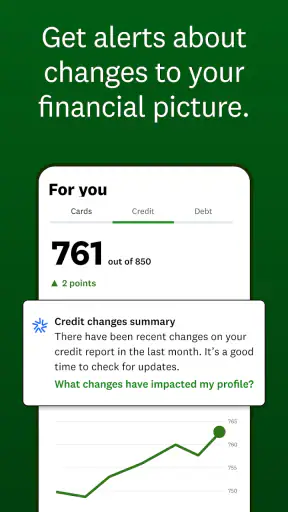
 Analysis by Getfullapps
I approached Intuit Credit Karma as a practical finance app rather than a magic solution to money problems. Its purpose is to help me understand my financial position and make more confident decisions, but that usefulness depends on how comfortable I am sharing financial information and how carefully I review what appears on screen. In my experience, the app makes the most sense for someone who wants a regular overview of credit-related information and financial options in one place, not for someone expecting a complete replacement for a bank, a budgeting notebook, or professional financial advice.
Credit Karma, LLC is the developer behind this free finance app. It has been available since February 28, 2013, and its current version is 26.30. The app is rated for Everyone and requires operating system 10 or later. Its scale is substantial: it has passed 50 million installs, with an average rating of 4.7 from around 3.2 million ratings and roughly 444 thousand written reviews. Those figures suggest that many people find the service useful, although popularity alone is not a reason to hand over sensitive information without reading the choices presented during setup.
How Credit Karma earns trust and where I stay cautious
I judge Credit Karma’s trustworthiness by how deliberately I use it, not simply by its popularity or polished presentation. Before relying on anything it shows, I make a habit of checking that the information matches the account or institution involved and of pausing before sharing more details or pursuing an offer. That cautious baseline makes the next question more useful: which everyday settings and routines help me stay informed without letting financial prompts take over?
A useful starting point for understanding my financial position
The strongest part of the experience is the way it gives financial information a more approachable shape. Credit topics can feel intimidating when I have to search through bank statements, lender portals, and unfamiliar terminology. A dedicated app creates a single place to return to, which is especially helpful when I am preparing to apply for credit, checking whether my financial profile has changed, or simply trying to become more aware of how lenders may view me.
I would not describe it as a complete financial command center. The app is better understood as a guided view into credit and related financial choices. That distinction matters. A person looking for detailed envelope budgeting, investment research, tax preparation, or day-to-day bank account management may need a different tool. Credit Karma can support those activities indirectly, but I would not use it as the only place to organize every financial decision.
The app’s broad appeal comes from reducing the effort needed to check in. Instead of waiting until I need a loan or card, I can make financial awareness a routine. That is a quieter benefit than an immediate offer or alert, but it is more valuable over time. Regular review can help me notice changes earlier and ask better questions before making a commitment.
Trust begins before the first useful screen
Finance apps deserve a stricter installation routine than casual entertainment apps. Before creating an account, I would check that the developer name shown is Credit Karma, LLC, confirm that the operating system requirement suits my device, and install only through the official app marketplace. The age rating of Everyone makes the app broadly accessible, but it does not mean every financial decision inside it is suitable for every person. A young or inexperienced user may still need an adult or qualified adviser to explain borrowing choices.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
During setup, I would slow down whenever the app asks for personal or financial details. The important question is not simply whether the app is free. The better question is what information is needed for the specific function I want to use, what choices are optional, and whether I understand why a particular detail is being requested. Free access should not replace careful consent. I prefer to read each screen instead of tapping through a long registration flow automatically.
That approach also helps separate the app’s core usefulness from the surrounding recommendations. A financial service may show products that appear relevant to my circumstances, but relevance is not the same as suitability. I treat every suggested card, loan, or other option as a prompt for research, never as a personal endorsement or a guarantee of approval.
Account controls matter more than a polished interface
My confidence in a finance app depends heavily on whether I can manage the account without confusion. I look for clear ways to review profile details, adjust communication preferences, manage connected information, and close or limit the account when I no longer want to use it. I also want sign-in and recovery steps to be understandable, because losing access to a financial account is stressful even when the app itself is not a bank.
Credit Karma is most useful when I make account maintenance part of the routine. I would review notifications rather than allowing every message to become background noise. If the app presents a new recommendation, I would open it deliberately, inspect the terms, and decide whether it is relevant. If I stop using a connected feature, I would look for a way to remove or disconnect it instead of leaving old access in place indefinitely.
A practical habit is to keep contact information current and avoid using an email address that I rarely check. Financial notices are easy to miss when they arrive in an abandoned inbox. I would also avoid signing in on shared devices and would use the device’s own security protections. These are ordinary precautions, but they make a larger difference than choosing an attractive theme or rearranging the home screen.
What I do during sensitive financial moments
The most important test comes when I am considering a product that could affect my finances. Suppose I am planning a move and want to understand whether applying for a new card makes sense. I might open Credit Karma to review my current position and explore what appears available, but I would stop before treating a displayed option as a final answer. I would compare the full terms, including fees, interest, repayment expectations, and eligibility conditions, using the provider’s own documentation before applying.
This workflow protects me from a common mistake: confusing a convenient recommendation with a complete comparison. An app can make discovery easier while still leaving the responsibility for the final decision with me. I would also avoid applying repeatedly just to test possibilities. Each application can have consequences, and the app should be a research aid rather than a button I press impulsively.
Another sensitive moment is a change that I do not recognize. If information looks unfamiliar, I would first check whether it could be a reporting delay, a recently updated account, or a simple data mismatch. I would not immediately assume fraud, but I would not dismiss it either. I would document what I see, review the relevant account directly, and use the appropriate support or dispute route. The app can help me notice a problem, but noticing is not the same as resolving it.
I am equally careful when using the service in public. I would not discuss account details over an open speaker, leave the app visible on a shared screen, or save sensitive screenshots in an unsecured photo library. A finance app can have sensible controls and still be exposed by the way I use my phone. Trust is partly a product question and partly a behavior question.
How I judge the information on screen
Credit-related information is easy to overinterpret. I would treat any score or profile view as an indicator for planning, not an absolute measure of my financial worth and not a promise that another lender will see exactly the same thing. Different lenders can use different criteria, and a displayed result may not answer every question I have about an application.
That is why I find trends and context more useful than a single number. If something changes, I want to know what action I should investigate: a balance change, a new account, a payment issue, or a reporting discrepancy. I would record important observations and verify major decisions with the company or institution involved. This prevents a common error in personal finance: reacting emotionally to one screen without checking the underlying details.
The app can also be helpful for people who do not yet have a strong vocabulary for credit. Explanations and guided presentation may make unfamiliar topics less intimidating. Still, I would search for the meaning of any term that affects a contract. A short explanation can introduce a concept, but it should not be the only basis for accepting a long-term obligation.
My data-sensitive routine
When an app handles financial information, I separate convenience from necessity. I ask myself what I want to accomplish today and whether I need to provide every requested detail to accomplish it. If I am only checking general information, I do not rush into optional recommendations or additional connections. If I choose to use a more personalized feature, I first make sure I understand the exchange: what I receive, what I share, and how I can later change my mind.
I also review the app after updates rather than assuming every setting remains exactly where I remember it. Version 26.30 is the current version, and keeping software current is sensible, but an update is a good reminder to revisit privacy choices, notifications, and account access. I would not treat an update number as evidence that the service is automatically right for me; it simply tells me which release I am using.
For households, I would keep profiles separate and avoid sharing login details. Even when two people manage money together, personal identity information and account recovery should not be mixed casually. A shared phone also deserves extra attention: screen locks, notification previews, and saved passwords can reveal more than intended.
Where it compares well with ordinary alternatives
The usual alternative is to visit separate lender websites, keep personal notes, and check information only when a major purchase is approaching. That approach gives me more direct contact with each provider, but it can be fragmented and easy to neglect. Credit Karma’s advantage is the lower friction of returning to one familiar app and using its presentation to decide what deserves attention.
A spreadsheet or paper notebook is better when I want complete control over a household budget. I can record cash spending, irregular bills, shared expenses, and goals without depending on a recommendation system. A bank’s own app is usually the better choice for transactions, balances, transfers, and account support because it is tied directly to the institution holding the money. Credit Karma sits between these options: more focused on credit awareness and financial discovery than a ledger, but less suitable for moving money or building a fully customized budget.
That middle position is both its strength and its limitation. I like having a guided starting point, especially when I am not sure which financial question to ask first. I would choose a spreadsheet when precision and flexibility matter more than convenience, and I would go straight to a lender or bank when I need authoritative account action or contractual clarification.
Who will benefit most from using it
I think the app is a good fit for someone who wants to become more attentive to credit without building a complicated system from scratch. It can suit a first-time borrower who wants to learn the language, a person preparing for a major purchase, or someone who wants a recurring reminder to review their financial position. It is also useful for people who prefer guided discovery over opening many separate websites.
The best results come from users who are willing to read carefully and make their own comparisons. I would recommend it to a friend as a starting point, particularly if that friend tends to avoid financial topics until a deadline creates pressure. A quick, regular check-in can make later decisions feel less mysterious.
I would advise caution for anyone who feels tempted by every personalized offer, wants a guaranteed approval, or dislikes sharing sensitive information with a financial service. Someone who needs detailed budgeting, direct banking, investing tools, or personal advice should look elsewhere or combine Credit Karma with a more appropriate specialist. It is also not the right choice for a person who will interpret every displayed estimate as a final lender decision.
Small habits that make the experience safer and more useful
My first habit would be to open the app with a question, not just curiosity. “Has anything changed?” is more useful than scrolling aimlessly. If I see something new, I would investigate the underlying reason and note any follow-up. This turns the service into a review tool rather than a stream of tempting suggestions.
My second habit would be to separate browsing from applying. I can learn about an option today and compare it elsewhere before taking action tomorrow. That pause is especially valuable when the product involves fees, interest, or a long repayment period. I would never let an attractive headline replace the full terms.
My third habit would be to audit access after a life change. If I change my email address, lose a phone, stop using a connected service, or suspect that someone else has accessed my account, I would update credentials and review account controls promptly. Waiting for a problem to become obvious is a poor strategy for any finance-related service.
Finally, I would keep a separate record of important decisions. The app may help me notice an opportunity or concern, but my own notes can preserve why I accepted, rejected, or postponed an option. That makes it easier to avoid repeating the same research and helps me evaluate whether the app is genuinely improving my decisions.
My cautious verdict
Credit Karma is a capable finance app for building credit awareness and exploring financial possibilities with less friction than a collection of disconnected websites. Its free price and broad availability make it easy to try, while its long presence and large user base explain why it has become familiar to many people. I appreciate the guided approach, but I would use it with a deliberate privacy routine and a healthy distance from personalized offers.
The central trade-off is simple: I receive convenience and a clearer starting point in exchange for engaging with a service that handles sensitive financial context. That exchange can be worthwhile when I understand the controls, review choices carefully, and verify important information elsewhere. It becomes less attractive when I want a private manual budget, direct bank operations, or independent financial advice.
My recommendation is therefore positive but measured. I would suggest trying it to a friend who wants a practical way to pay attention to credit and financial options, provided they treat the app as an informed companion rather than an authority. Use it to ask better questions, not to outsource the final decision. That mindset brings out its real value while keeping the most consequential choices firmly in the user’s hands.
Pros
- User-friendly interface for easy navigation.
- Free access to credit scores and reports.
- Personalized financial insights and tips.
- Real-time credit monitoring alerts.
- Customized recommendations for loans and cards.
Cons
- Limited support for non-U.S. users.
- Ads can be intrusive at times.
- Data privacy concerns for some users.
- Not all lenders participate in offers.
- Occasional inaccuracies in credit reports.
FAQs for Intuit Credit Karma
What is Intuit Credit Karma and how does it work?
Intuit Credit Karma is a financial app that provides free credit scores, reports, and insights to help users understand and manage their credit. It works by accessing your credit information from major bureaus and presenting it in an easy-to-understand format. The app also offers personalized recommendations for financial products based on your credit profile.
Is Intuit Credit Karma safe to use?
Yes, Intuit Credit Karma employs advanced security measures to protect user data, including encryption and secure connections. The app requires users to verify their identity, ensuring that personal information is accessed only by authorized individuals. Regular security audits are conducted to maintain the app's safety standards.
Does Intuit Credit Karma affect my credit score?
No, using Intuit Credit Karma does not affect your credit score. The app performs a 'soft inquiry' to access your credit information, which does not impact your score. However, if you apply for credit products through recommendations from the app, those could lead to 'hard inquiries' by lenders, which may affect your score.
Are the credit scores provided by Intuit Credit Karma accurate?
Intuit Credit Karma provides credit scores from TransUnion and Equifax, two of the major credit bureaus. While these scores are accurate reflections of your credit profile, they may differ slightly from scores used by lenders. It's important to check multiple sources and understand that scores can fluctuate based on recent credit activity.
What other features does Intuit Credit Karma offer besides credit scores?
In addition to free credit scores and reports, Intuit Credit Karma offers a variety of features such as credit monitoring alerts, personalized financial recommendations, and educational resources. Users can also access tools for tax filing, loan comparisons, and insights on how to improve their credit health over time.

Intuit Credit Karma
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via AppSupport@creditkarma.com, visit https://www.creditkarma.com, or review their http://www.creditkarma.com/about/privacy.










